

Netspend
by Netspend Corporation
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
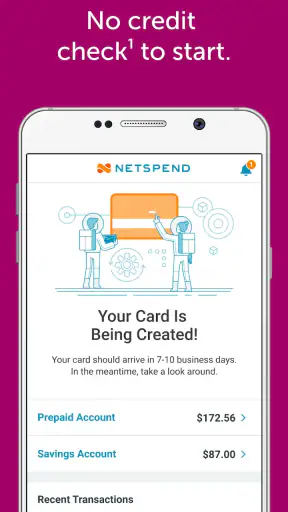
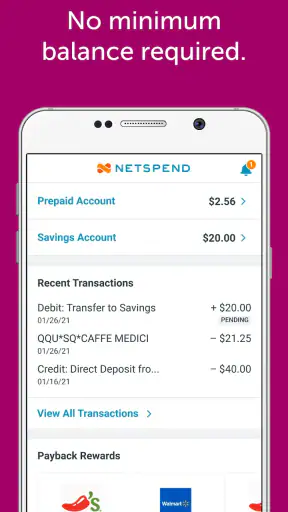
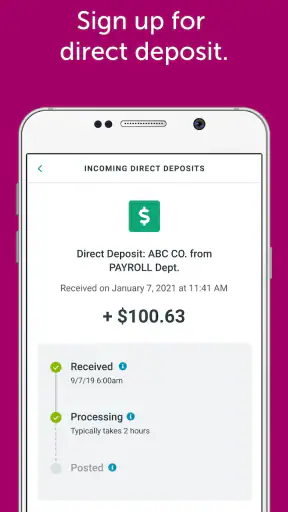
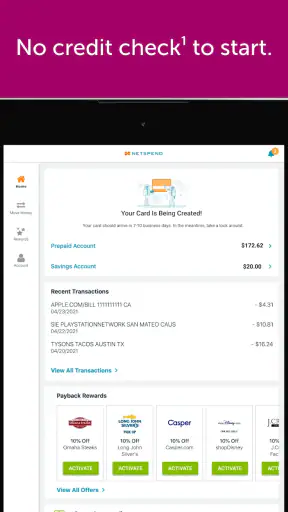
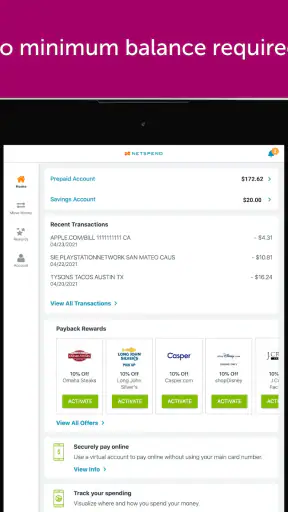
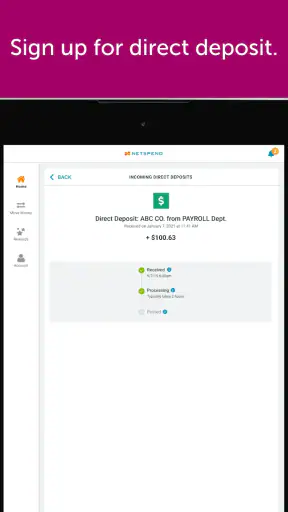
 Analysis by Getfullapps
When money has to work across a household, the difficult part is often not spending itself. It is keeping track of who is using which account, what balance is available, and whether a payment method is being treated as personal or shared. I found Netspend most useful when I treated it as a clear boundary around one person’s spending rather than as a complete family-finance command center. That distinction matters, especially when several people use the same phone or when a household needs to coordinate without mixing every transaction together.
Netspend is a free finance app from Netspend Corporation, designed around the company’s money-management service. It has been available since May 23, 2011, and its current version is 7.0.15 for devices running at least OS 9. The app is rated for Everyone, which makes it broadly approachable, although the financial decisions made through it still require adult judgment. Its average rating is 4.6 from around 175 thousand ratings, and it has passed 10 million installs, so this is not an obscure tool that only a few people have tried.
How Netspend fits into a shared household
I find Netspend most useful in a shared household when everyone treats it as one clearly defined money lane, not as a common pot that anyone can dip into. Before relying on it, I’d agree on who owns the account, what spending it covers, and how others should check in about purchases. That groundwork makes it easier to decide whether a separate account genuinely simplifies household routines.
A practical scenario for separate spending
Imagine a household where one adult handles regular bills, another manages day-to-day purchases, and a teenager occasionally needs access to money for transport or lunch. In that situation, putting every transaction through one shared phone or one general banking app can become confusing. A dedicated Netspend account can give one user a more visible spending boundary, while the household discusses transfers, deposits, or replenishment separately.
I would not describe this as a replacement for a shared budget. Instead, I see it as a way to make one stream of spending easier to observe. If someone is buying groceries, fuel, and small household items from the same balance, opening the app before a trip can provide a quick reality check. That simple habit is more valuable than trying to reconstruct spending at the end of the week from memory.
The shared-device angle needs care. If several people use the same smartphone, I would avoid leaving the account open between sessions. A finance app should be treated differently from a shopping or entertainment app, even when the phone belongs to the whole household. Each person should know whose account is active before checking a balance or reviewing activity. That small pause prevents an avoidable mix-up between personal and household money.
Why account boundaries matter more than convenience
Netspend works best when the account owner and the person using the app are clearly understood. A household can coordinate around the money, but that does not mean everyone should casually operate the same account. I recommend agreeing in advance about who checks the account, who adds money, and who is responsible for investigating an unfamiliar transaction. Those decisions are more important than the app’s basic navigation.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
For a couple, a useful arrangement may be one account for a defined category of spending, such as groceries or transport, while other expenses remain personal. For roommates, the same approach can help with a shared recurring need, but only if everyone agrees on the contribution process. I would be cautious about using one account as a general-purpose pool when several people have equal access and no written understanding of what the balance is meant to cover.
This is one of the app’s practical trade-offs. A focused account can make spending easier to follow, but it can also create extra coordination. Someone may need to ask before using the remaining balance, and another person may need to check whether a recent transaction has settled. That is not a flaw unique to Netspend; it is the natural cost of separating money by purpose rather than treating one balance as unlimited household cash.
Setting it up without blurring responsibilities
My preferred setup begins with a short household conversation before anyone starts using the account. Decide whether it belongs to one person, serves a shared category, or is being used temporarily for a particular spending goal. Then decide who keeps the login details private and who is allowed to view activity. Writing these rules down in a note can be surprisingly helpful when the same phone is passed around.
I would also label the account’s purpose in ordinary language outside the app, such as “weekly household purchases” or “personal spending.” That prevents the balance from being mistaken for emergency savings, bill money, or another person’s funds. The app can show the account activity, but it cannot settle a household disagreement about what the balance was intended for.
Before relying on it for an important purchase, I would open the app, review the available balance, and make sure the account information belongs to the right user. This is especially useful after another household member has handled the phone. A quick check is less frustrating than discovering at checkout that the wrong account was selected or that the expected amount is not available.
Another sensible habit is to review activity at a fixed time rather than constantly checking it. For a shared spending account, a brief review after shopping or at the end of the day can identify mistakes while the details are still fresh. If something looks unfamiliar, ask who used the account before assuming fraud or blaming another person. The app provides a place to inspect activity; good household communication provides the context.
Coordinating money without turning the app into a group chat
Netspend can support coordination, but I would not expect it to replace a family calendar, shared notes, or direct conversation. If one person adds money for groceries, another person still needs to know that the balance is available for that purpose. If the account is used for a child’s occasional expenses, the adult should explain what the money is intended to cover instead of assuming the app itself will communicate those limits.
A simple routine works well: agree on the spending category, confirm the amount before a purchase, and check the account afterward. This is particularly useful when the device is shared and notifications or recent activity may be seen by more than one person. Coordination should happen through an agreed household channel, not through assumptions about who happened to open the app last.
There is also a useful distinction between visibility and permission. Seeing an account balance does not automatically mean someone should be allowed to spend from it. Likewise, knowing that a purchase occurred does not explain whether it was authorized. I think households get better results when they decide these boundaries first and use Netspend as an account-management tool, not as a substitute for those decisions.
Age, trust, and the Everyone rating
The Everyone content rating makes the app accessible from an age-classification standpoint, but I would not interpret that as a recommendation for unsupervised financial use by children. Money apps involve real consequences: a mistaken purchase, a misunderstood balance, or a shared login can create problems even when the interface itself is easy to understand.
For a teenager, I would introduce the app alongside clear expectations. Explain the difference between available money and promised money, show how to review activity, and make sure the young user knows whom to contact when a transaction looks wrong. The goal is not simply to hand over access. It is to build a routine in which the user checks before spending and reports issues promptly.
Trust should grow from observable habits rather than from age alone. A young person who regularly checks purchases and asks before using shared funds may be ready for more independence than an older user who ignores account boundaries. Netspend can be part of that learning process, but it does not make the judgment for the household. I would still keep sensitive credentials private and avoid treating a shared phone as proof that everyone has equal authority.
For adults sharing a device, the same principle applies. A spouse, partner, or roommate may be trusted completely and still need separate access arrangements. Mistakenly opening the wrong account is enough to create confusion, especially when several people are checking balances in a hurry. I prefer deliberate sign-out or account switching practices whenever the phone changes hands.
What it does well in everyday use
The strongest part of Netspend, in my experience, is its focus. It is easier to think about a defined spending balance when that balance is not buried among unrelated financial products, investment information, or a large collection of banking tools. For someone who wants a straightforward place to check and manage Netspend-related money, that focused approach can feel less intimidating than a traditional bank app.
It is also useful for a person who wants a separate spending lane. A household member can use it for routine purchases while keeping other finances distinct. That separation makes conversations more concrete: instead of arguing over every transaction in a general account, the household can discuss the purpose and balance of one specific account.
The long availability of the service and its broad user base are reassuring in a limited sense. The app has been around since 2011, and its current release shows that it continues to be maintained. I would still judge it by whether its account model fits my needs, rather than choosing it solely because many people have installed it.
Where the experience can feel restrictive
The same focus that makes Netspend approachable may feel limiting to someone who wants a full financial dashboard. If your priority is comparing several bank accounts, tracking investments, planning complex household budgets, or viewing every financial relationship in one place, a conventional banking app or dedicated budgeting service may be a better fit.
Shared use can also expose friction. One account used by several people requires communication, and a shared phone increases the chance of opening the wrong session or exposing information to the wrong person. I would not choose this arrangement for a household that wants completely informal access, because the convenience of “everyone can just use it” is exactly what can make responsibility unclear.
There is a second trade-off for people who need detailed financial records. A spending app can help you see activity, but it does not automatically create a household agreement, explain every purchase, or decide how costs should be divided. If you need formal expense sharing among roommates, a shared spreadsheet or bill-splitting tool may still be necessary alongside Netspend.
I would also skip it if my main goal were to teach a child that all household money is available on demand. The app may be suitable for supervised access to a defined amount, but the household must provide the limits and the education. The Everyone rating does not remove that responsibility.
How it compares with usual alternatives
Compared with a standard bank app, Netspend feels more specialized. A bank app is usually the natural choice when I need a broad view of checking, savings, transfers, and other services from one institution. Netspend makes more sense when I want to manage the Netspend account itself and keep a particular spending purpose separate from the rest of my finances.
Compared with a budgeting app, the difference is even clearer. Budgeting software is generally built around categories, goals, reports, and a wider picture of income and expenses. Netspend is better understood as an account-centered tool. If I want to know how much is available for a defined spending stream, it can be practical; if I want to forecast several months of household cash flow, I would look elsewhere.
Compared with informal cash sharing, the app offers a more trackable routine, but it also demands better digital habits. Cash can be handed over without a login, yet it is easy to forget where it went. A digital account can make activity easier to review, while creating new responsibilities around device access and credentials. For me, that is a worthwhile exchange only when the household agrees on the account’s purpose.
Small habits that make the app more useful
I would begin every shared-device session by checking the account identity and end it by returning the phone to a neutral state. I would never rely on memory for the account’s purpose, and I would keep a separate household note for agreed contributions or spending limits. These habits are simple, but they address the problems that a finance app cannot solve on its own.
For recurring household purchases, review the balance before leaving home rather than waiting until the payment moment. Afterward, compare the activity with the receipt while the purchase is still easy to remember. That two-step workflow catches both ordinary confusion and genuine irregularities earlier than a monthly review.
For a younger user, make the first few uses instructional. Ask the user to identify the account, check the balance, describe the planned purchase, and review the result afterward. This turns the app from a mysterious payment window into a practical lesson about responsibility. It also gives the adult a chance to see whether the arrangement is working before granting more independence.
Finally, keep personal and shared purposes visibly separate. If the same household member uses Netspend for personal spending and also contributes to a shared category, mixing those intentions can make every later conversation harder. A clear purpose is the best protection against a balance being misunderstood.
My household verdict
Netspend is a sensible choice when I want a focused finance app for a defined account and a clear spending boundary. Its free access, Everyone rating, established history, and current version make it easy to consider, while the strong user response suggests that many people find the basic experience useful. I especially like it for adults who need a straightforward way to check and manage one spending stream without turning the task into a full financial-planning project.
For household use, my recommendation comes with conditions. Keep account ownership clear, agree on who may spend, protect access on shared devices, and teach younger users that the app is a tool rather than permission to use any available money. If those boundaries are in place, it can support practical coordination without forcing every household expense into one account.
I would choose a broader bank app for complete financial visibility, a budgeting tool for detailed planning, or a bill-sharing service for formal roommate accounting. But when the goal is narrower—managing a Netspend account and keeping a particular balance understandable—I think this app earns its place. Its real strength is not trying to manage the entire household; it is making one money lane easier to see and use responsibly.
Pros
- Fast mobile check deposit for eligible users
- Customizable transaction alerts help monitor account activity
- Offers prepaid cards without requiring a traditional bank account
- Multiple card designs and account options are available
- In-app support makes it easy to find help when needed
Cons
- Some features and services may vary by state or card type
- ATM withdrawals can include fees, especially outside the network
- Cash reload locations may charge additional service fees
- Account approval and verification may require personal documentation
- Not ideal for users seeking savings, investing, or full banking tools
FAQs for Netspend
What is Netspend, and what can I use it for?
Netspend is a financial service that provides prepaid debit cards and a mobile app for managing everyday spending. After setting up an account, users can typically check their balance, review transactions, receive alerts, deposit money, and transfer funds where supported. It can be useful for budgeting or avoiding traditional bank accounts, but availability, fees, and features may vary by card and location.
Is the Netspend app free to download and use?
The Netspend app is generally free to download from the official Android or iOS app store, but using the associated prepaid account may involve fees. Depending on your plan and activity, charges can apply for monthly service, ATM withdrawals, cash reloads, expedited transfers, or other services. Review the current fee schedule carefully before ordering a card or adding money.
How do I add money to my Netspend account?
Netspend may support several funding methods, including direct deposit, bank transfers, mobile check deposit, tax refunds, and cash reloads at participating locations. The options available to you can depend on account verification, card type, and eligibility. Before choosing a method, check processing times, minimum or maximum limits, and any applicable deposit or reload fees shown in the app.
Is Netspend safe for managing money and making purchases?
Netspend uses account security features such as login protection, transaction monitoring, notifications, and the ability to report or manage a card through the app. These tools can help you identify unauthorized activity quickly, but no financial service is completely risk-free. Use a strong password, protect verification codes, avoid suspicious links, and contact Netspend promptly if your card or account information is compromised.
What should I do if my Netspend card is lost, stolen, or a transaction looks incorrect?
If your card is lost or stolen, use the Netspend app or contact customer support as soon as possible to lock or replace it, depending on the available options. For an unfamiliar transaction, review the details and report it through the official support channels. Keep in mind that investigation procedures, replacement costs, and protections may depend on when you report the issue and the circumstances involved.

Netspend
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via feedback@netspend.com, visit https://www.netspend.com, or review their https://www.netspend.com/help/privacy-policy/.










